Search
A hand reaches toward a staircase of rising U.S. dollar bills.

Two Reasons Why Waiting to Buy a Home Will Cost You

Sandy Ginn January 19, 2022

If you’re a homeowner who’s decided your current house no longer fits your needs, or a renter with a strong desire to become a homeowner, you may be hoping that waiting until next year could mean better market conditions to purchase a home.
 
To determine whether you should buy now or wait another year, you can ask yourself two simple questions:

  1. Where will home prices be a year from now?
  2. Where will mortgage rates be a year from now?
Let’s shed some light on the answers to both of these questions.
 

Where Will Home Prices Be a Year from Now?

Three major housing industry entities are projecting ongoing home price appreciation in 2022. Here are their forecasts:
 
According to the National Association of Realtors (NAR), the median price of a home today is $353,900. Using an average of the three price projections above (6.5%), a home that sold for $353,900 today would be valued at $376,904 at the end of next year. As a prospective buyer, you would therefore pay an additional $23,004 by waiting.
 

Where Will Mortgage Rates Be a Year from Now?

Today, Freddie Mac announced their 30-year fixed mortgage rate was at 3.1%. However, most experts believe mortgage rates will rise as the economy recovers. Here are the forecasts for the fourth quarter of 2022 by the three major entities mentioned above:

That averages out to 3.7% if you include all three forecasts. Any increase in mortgage rates will increase your costs.
 

What Does It Mean for You if Home Values and Mortgage Rates Increase?

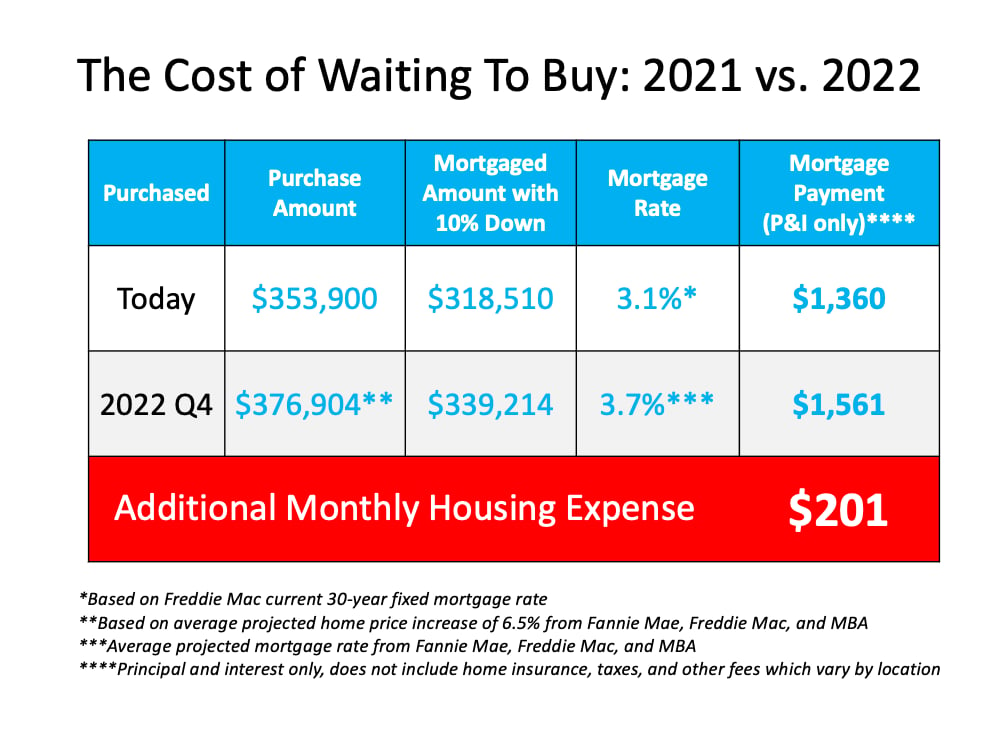
If both variables increase, you’ll pay a lot more in mortgage payments each month. Let’s assume you purchase a $353,900 home today with a 30-year fixed-rate loan at 3.1% (the current rate from Freddie Mac) after making a 10% down payment. According to mortgagecalculator.net, your monthly mortgage payment would be approximately $1,360 (this does not include insurance, taxes, and other fees because those vary by location).
 
Infographic compares homebuying costs today and in 2022 Q4, showing a $201 higher monthly payment.
 
That same home one year from now could cost $376,904, and the mortgage rate could be 3.7% (based on the industry forecasts mentioned above). Your monthly mortgage payment after putting down 10%, would be approximately $1,561.The difference in your monthly mortgage payment would be $201. That’s $2,412 more per year and $72,360 over the life of the loan.
 
Add to that the approximately $23,004 a house with a similar value would build in home equity this year due to home price appreciation, and the total net worth increase you could gain by buying this year is over $95,364 (the $72,360 mortgage savings plus the $23,004 potential gain in equity if you buy now).
 

Bottom Line

When asking if you should buy a home, you may think of the non-financial benefits of homeownership. When asking when to buy, the financial benefits make it clear that doing so now is much more advantageous than waiting until next year.

Recent Blog Posts

Dark blue house with a lit dormer and landscaped lawn beneath a colorful dusk sky.
New Construction in Greater Indianapolis: Understanding Your Options

From custom builds to move-in-ready homes, explore your new construction options in Greater Indianapolis and what to consider before choosing the right home.
White two-story home with black shutters, a wood entry door, and landscaped hedges.
Your Dream Home Might Not Be on the MLS

Some of the best homes never appear in online listings. Discover how a proactive search strategy and local connections can uncover hidden opportunities.
Autumn-decorated front porch with a dark door, colorful mums, and pumpkins.
Your Guide to Creating a Cozy and Welcoming Home This Fall

Simple seasonal touches can bring warmth, comfort, and connection to your home, creating inviting spaces for family and friends all fall long.
Lakefront docks and pontoon boats line a wooded shore beneath a pastel sunset sky.
Preparing Your Lake Home for the Off-Season: A Complete Guide for Seasonal Homeowners

From winterizing water systems to storing lake gear, a little off-season preparation can protect your lake home and make your spring return much easier.
Open-plan living room and kitchen with a fireplace and large lake-view windows.
In Today’s Market, Presentation Is Everything

From thoughtful staging to professional photography, the way your home is presented can make all the difference in attracting buyers and maximizing its value.
Two-story brown house with cream trim, multiple gables, a covered porch, and attached garage.
Beyond the Staging: What Every Buyer Should Look for When Touring a Home

A beautiful first impression matters, but knowing what to look for beyond the finishes can help you choose a home that truly fits your lifestyle.
Urban plaza at dusk with brick office buildings, restaurants, and illuminated outdoor seating.
Why Buyers Are Choosing Greater Indianapolis—and Staying for the Long Run

National recognition, strong communities, and everyday livability are making Greater Indianapolis a place buyers choose to call home for the long run.
A family fishes from a wooden dock as a woman paddles a canoe nearby.
The Quiet Luxury of a Second Home: Why It’s Becoming One of the Most Meaningful Investments You Can Make

More than a getaway, a second home offers lasting memories, meaningful family connections, and a lifestyle centered on time well spent.
Light blue-gray two-story home with white trim, a covered entry, and a two-car garage.
What Is the Homestead Exemption in Indiana — and Why Is It So Important?

One simple filing can significantly reduce your Indiana property taxes. Here’s what every homeowner should know about the Homestead Exemption.

Work With Us

With experience in every type of real estate transaction, we aim to deliver sound advice, extensive research, and tenacious negotiating in order to secure incredible results for our clients. Every opportunity to serve our clients is a beautiful gift worth cherishing.